
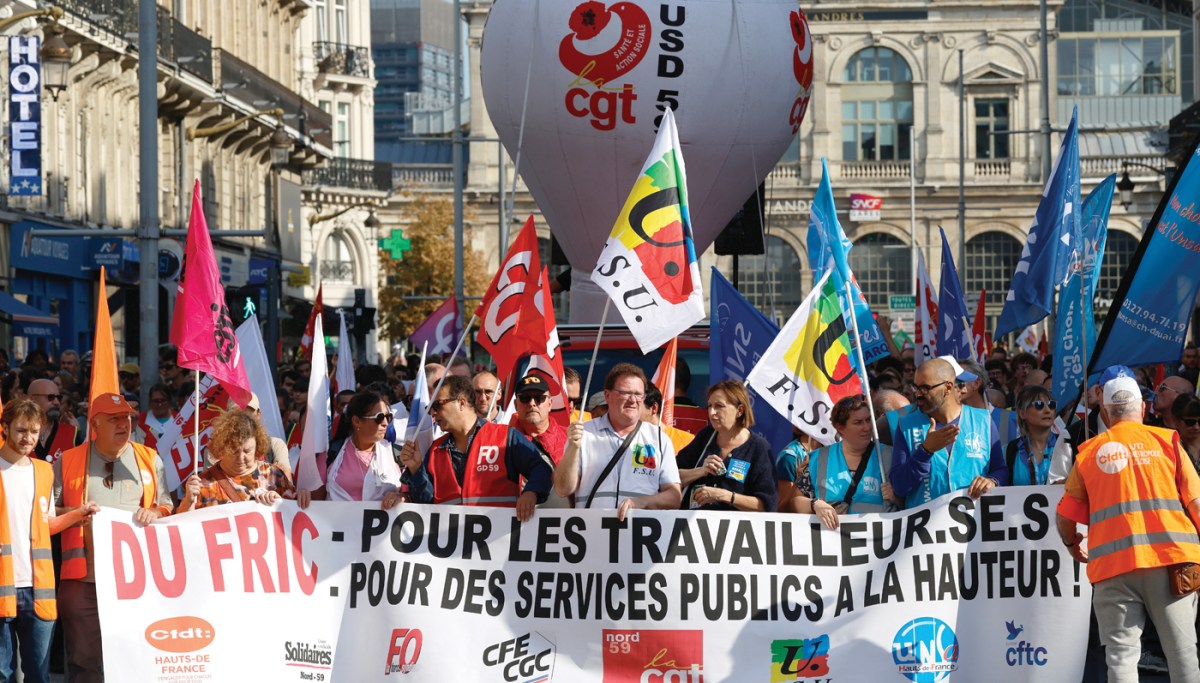
Nominally, the latest crusade to corral union workers, pensioners, students, and Greta Thunberg on the streets is something about education. Really, it’s a not-so-veiled threat to the government that it better not dare to reform France’s truly disastrous fiscal order. It’s also an attempt to stop, through mob violence, the French government from responding to a global investor revolt over its Obligations Assimilables du Trésor — medium- to long-term government bonds issued by the French Treasury to finance the national debt.France’s bond crisis portends the very worst for the United States: the OAT sell-off demonstrates what would happen if we didn’t maintain the exorbitant privilege of the world’s reserve currency. It also shows what will happen when we hit widespread entitlement solvency, assuming the bipartisan consensus — that we continue to take on new debt to fulfill scheduled benefits — holds constant. We can ignore the actual protests in their entirety as long as we understand they were enacted in response to Prime Minister Sebastien Lecornu’s proposed 2027 budget, which sought 54 billion euros in savings. That move was, in turn, a response to investor fear over France’s current 5.4% deficit-to-GDP ratio. Lecornu’s pitch would freeze public-sector wages while hiking taxes with the goal of constraining 2027’s deficit-to-GDP ratio to 5%, as opposed to the 6.5% projection, should fiscal reform fail. Protesters march against the government’s release of next year’s draft budget, in Lille, France on Sept. 29. (Jean-Francois Badias/AP Photo) The chaos in the streets is responding to the budget proposal. But the chaos in the bond market is responding to the political blowback against that proposal, not the idea itself. With the opposition parties roundly refusing reform and the riots only gaining international plaudits, the French benchmark 10-year OAT rose from around 4.25% in the first half of September to more than 4.85% by mid-October, first peaking at a 24-year high of nearly 5%.And the funny thing about the French fiscal crisis is that in some respects, the U.S. is already in worse shape. Our 10-year yield peaked at our 24-year high of over 5.3% earlier this month, and our deficit-to-GDP ratio for the just-ended fiscal 2026 was an atrocious 6.2%. But France is currently careening toward a full-scale debt crisis that has prompted its leading far-left presidential candidate to call for outright defaulting on its debt, while the U.S. remains comfortable enough that both parties are bragging about future spending sprees.There are three differences: currency, economic growth, and time.Contrary to the musings of Vice President JD Vance that the dollar’s reserve status poses a “resource curse,” the greenback’s ubiquity means that banks, governments, and investors around the world have an artificial demand for dollar-denominated assets, the most liquid being U.S. Treasurys. This means that even when our fiscal house isn’t in order, the floor for the Treasury investor base is much higher than that of OATs.Then there is economic growth and the government spending which crowds it out. The U.S. spends about two-fifths of its annual economic output on the government at all levels. France spends nearly three-fifths. It is thus not a coincidence that whereas the U.S. is averaging over 2% real annual economic growth, the French gross domestic product growth rate last quarter was zero.THE POPE AND THE RIOTS: A CLASH OF CIVILIZATIONS IN PARISBut the problem for the U.S. is time. The driver of our government deficit is mandatory spending, and though the impending insolvency of Social Security and Medicare should serve as automatic brakes when both programs go bankrupt within the next decade, both parties seem eager to take on new debt to finance the scheduled benefits. Should Congress and the president decide to add $25 trillion in new debt only to finance the Social Security cash-flow shortfall over the next 30 years — that’s not including the projected $21 trillion of interest costs that would accompany it — economic growth would need to double or triple to stabilize our national debt.The U.S. is lucky to have a bevy of supply-side reforms to couple with entitlement reform before entitlements go bust and bring our bond market to the brink. But France is out of time and out of money. With zero economic growth and the entire population dependent on the government dole, France’s only option is to slash spending or, as the socialists dream, default and devolve into international irrelevance.Tiana Lowe Doescher (@TianaTheFirst) is an economics columnist for the Washington Examiner.
Why France’s financial crisis foreshadows what will come in the US without King Dollar and reform
Full Article
Original Source
Read the full article at Washingtonexaminer →KhanList aggregates and links to publicly available news content. We do not host full articles from third-party sources. Always verify important information with original sources.