
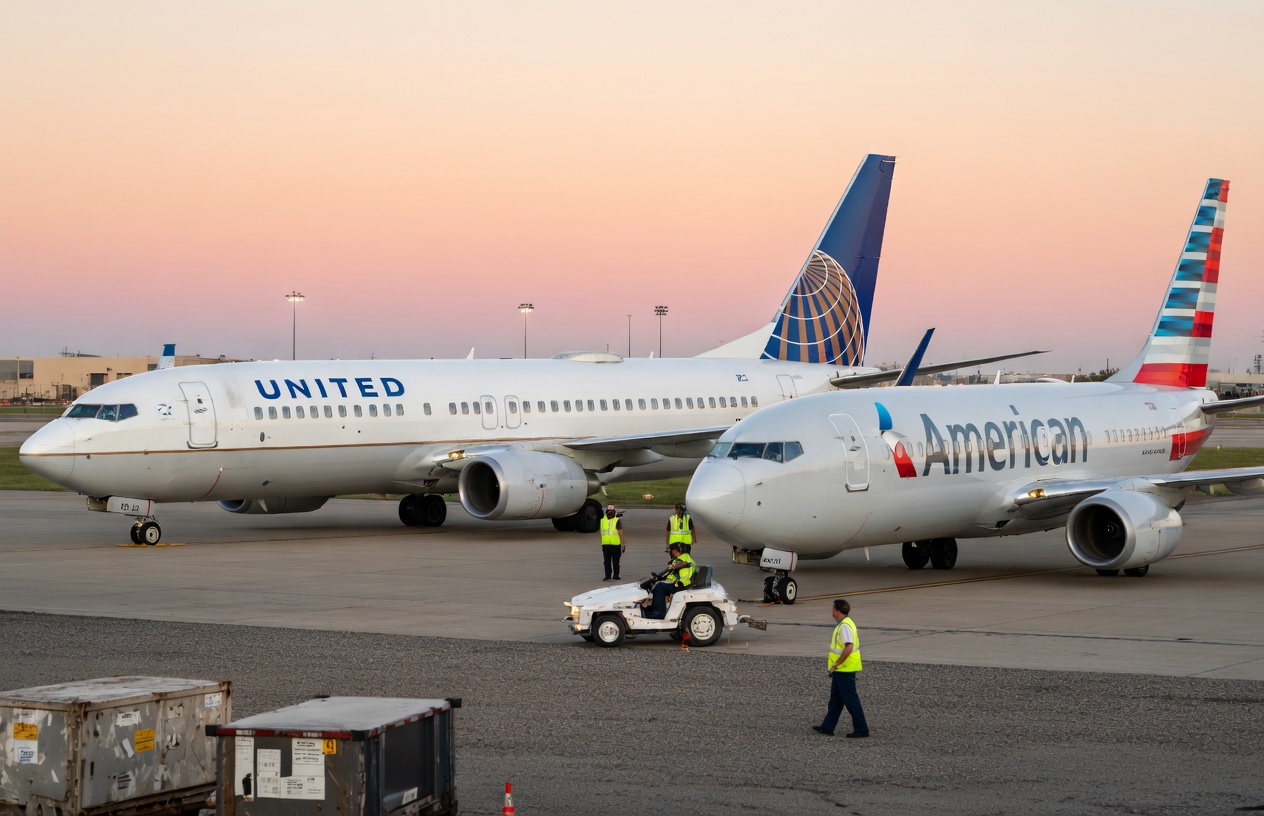
One Mile at a Time points to a new Claude-assisted analysis trying to put data behind United Airlines CEO Scott Kirby’s claim that American Airlines is losing more than $1 billion per year in Chicago and will eventually be forced out by “economic gravity.” Every article I read on the American vs United fight at Chicago O'Hare was surface-level. UA's Scott Kirby says AA loses ~$1B/yr at ORD, AA denies it, no reporter checks. I had @claudeai pull the data and do the math🧵 pic.twitter.com/xhM4M97NNh — late stage capitalist (@bentboolean) August 29, 2026 This analysis finds that United sells domestic Chicago tickets for 10.5% more per passenger mile than American. Then the analysis substitutes modeled revenue for the ticket revenue it found, guesses fleet and cost inputs that are available in federal data, and creates American’s billion-dollar loss by assuming United breaks even and assigns $2.8 billion in missing expenses to a much smaller American operation. Kirby is surely right that American earns an inferior return on its O’Hare assets. It earns an inferior return on all its assets, it does not make money as a company roughly speaking. Indeed, it’s earning billions of dollars from Citibank and still breaking even so its losses moving passengers, planes and cargo are in the billions. Importantly for understanding Kirby’s claims, this new work doesn’t show American losing $1 billion at O’Hare that it could save by closing the hub. Kirby’s Chicago Loss Number Keeps Growing Kirby said late last year that American was losing about $800 million annually at O’Hare. Leaked American figures reportedly showed a roughly $70 million second-quarter loss after domestic and international results were combined which isn’t great but nowhere close to that annual run rate. In February, Deutsche Bank analyst Michael Linenberg estimated that United generated about $10 billion of Chicago-linked revenue at a 5% operating margin, while American generated just over $5 billion at a negative 9% to 10% margin. That implied around $500 million of profit for United and a $450 million to $500 million loss for American. It was an estimate built from public airline financial and operating data. Kirby now says American lost $1.1 billion during the 12 months leading into the first quarter and will do worse as its new flights mature. I wrote earlier this week that American isn’t going anywhere, and isn’t likely to be forced to. American needs Chicago to work, while United wants the gates, feed and pricing power that would follow if its major competitor in the market left. Ticket Data Is Useful The analysis starts with the federal government’s Origin and Destination Survey, known as DB1B. Airlines report a 10% sample of tickets each quarter, including fare, passengers, mileage, origin, destination and the airline selling the ticket. This is a goldmine for studying domestic fares. It doesn’t show airport profit, loyalty revenue, or cargo. The author filtered the second quarter of 2025 to 203,378 lower 48 markets beginning at Chicago O’Hare. United produced 26.56 cents of ticket value per passenger-mile, compared with 24.04 cents for American. United also led on 16 of 18 large routes both carriers flew non-stop. That strongly suggests United has a local pricing advantage in Chicago. It’s not an airport revenue calculation, though. A passenger traveling Des Moines – Chicago – New York starts their journey in Des Moines and isn’t in this data. Connecting passengers are a big part of hub economics. And you can’t just assume the airline would capture that revenue somewhere else (connecting the same passenger through a different hub). The fare amount in the data is also a mileage-prorated piece of the whole ticket and includes taxes and government fees. And second-quarter 2025 was the final DB1B quarter. DOT replaced it with a monthly 40% sample called DB1C beginning in July 2025. The Analysis Changes Revenue Bases Midway Through The ticket sample produces about $33.4 million of American ticket value and $47.2 million for United. Multiplying the 10% sample by ten and annualizing the quarter gives approximately $1.34 billion and $1.89 billion of Chicago-origin Lower 48 ticket value. The later profit table suddenly reports $4.39 billion for American and $5.66 billion for United. Those figures are not an expansion of the ticket sample. They come from multiplying local ticket yield by an assumed 84% load factor, modeled seats and peak daily departures. This applies the yield of Chicago-origin cash tickets to every occupied seat, including connecting passengers, award passengers and other traffic the sample excluded. The cost work has the same problem. The report converts the operating-carrier share of local nonstop passengers into a mainline-versus-regional departure mix. Regional jets disproportionately carry connections, so local passenger share is not representative of the hub. It treats each regional airline’s aircraft operating cost as American’s or United’s cost. It calls Form 41 aircraft expense “all-in” cost even though the schedule omits passenger service, ground handling, airport charges, distribution and corporate administration. It includes depreciation and rentals, so the resulting spread isn’t variable margin either. United’s margin advantage is 2.66 cents per seat-mile. The revenue difference supplies 2.12 cents, or 80%. The modeled cost difference supplies 0.54 cents, or 20%. The report calls this two-thirds revenue and one-third cost. Then the piece assumes United’s $2.82 billion aircraft margin is entirely consumed by other expenses, making United break even, then assigns American the same $2.8 billion despite American being about 20% smaller in the model. One Mile at a Time says United breaking even is what Kirby “essentially seems to be hinting at.” Kirby has actually said the opposite. Kirby has said United earned about $500 million in Chicago in 2025 and would have earned roughly $600 million without the fight over new American capacity. That implies $2.32 billion (not $2.8 billion) in expenses missing from the model. Subtract the same $2.32 billion from American’s claimed $1.84 billion aircraft margin and the result is a $480 million loss, almost right on Deutsche Bank’s estimate. Scale those expenses to American’s smaller operation and the loss falls further. (That’s probably not right, either, but it suggests the report is building its result from an assumption which is contrary to the airline’s claimed public statements that I trust if only for avoidance of securities fraud reasons.) Where American’s Chicago “Loss” Actually Comes From American CFO Devon May laid out the airline’s accounting in March. Every American hub covers its direct operating expenses. Every hub remains profitable after aircraft ownership, scheduled maintenance, airport rent and hub-specific fixed costs. Some hubs become unprofitable (including Chicago) after American allocates systemwide overhead. What Gets Charged To ORD American’s Result What It Answers Flight contribution Fuel, crews and direct flight expense Profitable Do the flights cover the costs of operating them? Hub contribution Flight costs plus aircraft ownership, maintenance, airport rent and ORD fixed costs Profitable Does Chicago cover the assets and expenses tied to Chicago? Fully allocated profit Hub costs plus a share of headquarters, technology, sales and other system expense Losses, Deutsche estimated −9% to −10% Where does American assign its companywide failure to cover overhead? Decision to shrink Costs actually eliminated, value of aircraft redeployment, and lost network and loyalty contribution Unknown Would American earn more with the assets somewhere else? Every hub can be making a positive contribution and American can still break even. The network covers flight, aircraft and local costs while corporate overhead consumes it all. Kirby’s billion dollar loss is basically allocating American’s systemwide costs to Chicago. Closing the hub doesn’t eliminate Skyview headquarters, the tech stack, sales or administrative expenses. Those costs would get redistributed to Dallas, Charlotte, Miami and the rest of the network. Some might get removed over time, but there’s no $1.1 billion for American to save by leaving (or de-hubbing) Chicago. And if they did that they’d also lose revenue that doesn’t get credited to Chicago. The hub supports connections elsewhere in the network and gives AAdvantage relevance to Chicago customers. American reported $6.2 billion of 2025 cash from co-brand and other partners. The timing of Citi’s renewal payment matters here. American’s $6.1 billion partner-cash total for 2024 included a one-time payment tied to the re-upping of the cobrand deal. The $6.2 billion received in 2025 didn’t include this payment, so it’s a reasonable recurring base. Assume cards supply 90% to 95% of partner cash and Chicago represents 3% to 5% of the card franchise. That attributes $170 million to $295 million of annual card-related cash to the local market. American’s new Citi agreement implies about 34% marginal pre-tax flow-through, producing roughly $55 million to $100 million. A broad allocation based on O’Hare’s share of system flying produces $390 million to $470 million of card cash and $130 million to $160 million of contribution. It’s plausible Chicago represents twice as much as that. Card Attribution Annual Revenue Pre-Tax Contribution Chicago local franchise $170–$295 million $55–$100 million Broader network allocation $390–$470 million $130–$160 million American And United May Both Be Under-Earning At O’Hare Deutsche Bank’s estimated 5% United Chicago operating margin was well below United’s 9% system operating margin in 2025. United says its response to American’s growth reduced Chicago profit from around $600 million to $500 million. It willingly made the hub less profitable to preserve gates and deny American the schedule breadth it needs to rebuild market share. United’s loyalty economics complicate its claims about American too. The airline recognized about $3.2 billion of MileagePlus partner marketing and related revenue in 2025, equal to 5.4% of total revenue. Mechanically applying that share to Deutsche Bank’s $10 billion Chicago revenue estimate produces $540 million which is United’s entire claimed Chicago profit. That doesn’t prove United’s transportation operation at O’Hare breaks even. But we can’t compare hub profitability without disclosing whether loyalty, cargo, international feed and network contribution are included. United can’t really credit those economics when describing its own hub profits while excluding them when declaring American’s doomed to economic gravity. American’s real decision is whether Chicago’s hub contribution, network value and card relevance exceed the profit it could earn by moving aircraft and capital elsewhere. United’s decision is whether accepting below-system returns today buys enough gates, feed, corporate business and future pricing power to justify the investment. Those are opportunity cost questions. They don’t describe an American hub hemorrhaging $1.1 billion of avoidable cash and waiting for “economic gravity” to force them out. Topics on this page
United Wants American Airlines Out Of Chicago—AI Backs Its $1.1 Billion Loss Claim By Inventing $2.8 Billion In Costs
Full Article
Original Source
Read the full article at Viewfromthewing →KhanList aggregates and links to publicly available news content. We do not host full articles from third-party sources. Always verify important information with original sources.