
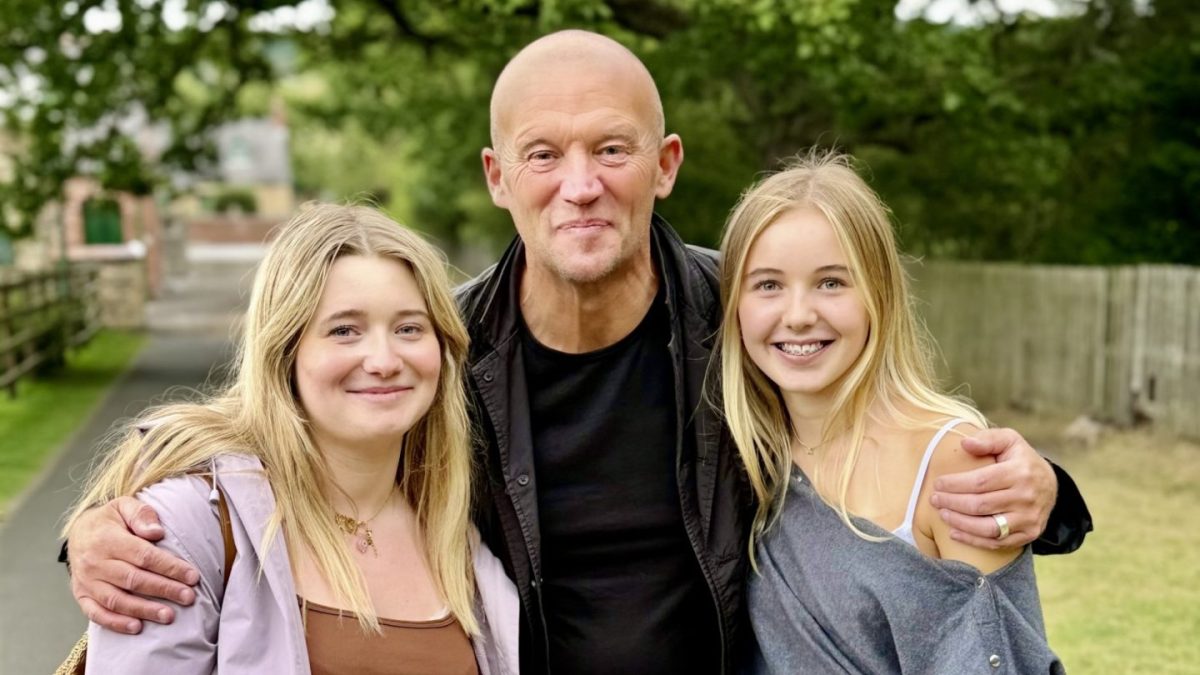
Stuart Fearn is 57 and already has a pension pot that nearly has £1m in it. Although he could retire with this amount and get by, he has decided against it. Like many of his peers, he is opting for semi-retirement – reducing his hours, instead of stopping work entirely. The father-of-three, from North Shields in the north east of England, said the fact he does not have “the greatest history of health” contributed to his decision to cut down his hours as a banking technology specialist around three or four years ago, and now he works around 20 per week. Shorts He was working in a senior role at a banking platform, and he says reducing his hours but not quitting entirely has allowed him to slowdown and enjoy his life more, while not reducing his family’s disposable income by as much as he would do if he retired. The extra time has allowed him to do charity work. He is a trustee of the Society Matters Foundation, and Patterdale Estate – both based in the north east. “I knew I needed to be strict and follow the plan, which is to reduce work – not stop – but continue to do the things I love so I can enjoy life,” he said. Stuart lives with his wife Kirsty, 50, and his youngest daughter Ava, 16. He has two other children, who live away from home, and he is also a grandfather-of-three. “I don’t want to negatively impact our family’s lifestyle too much as we love going on holiday,” he explains. He added: “I still have a young wife and daughter at home, and the cost of living isn’t reducing. This means my income for now still has to be enough to cover our lifestyle.” His exact earnings fluctuate as he also does some work for other contacts in the banking and technology industries alongside his salaried work, but he expects overall to remain a higher-rate taxpayer, earning over £50,270 per year. His aim is to end up with around 70 per cent of the income coming from work and the rest coming from savings when required. At the moment, he is not touching his pension at all, and is relying on other investments and savings he has set up to supplement his income. Most of his savings – around 90 per cent – are held in pensions, which he started paying into very early in life while working in the railway industry for the National Railway. Here, he got a defined benefit (DB) – or final salary – pension, which gives him an income for life. He has another pension from his finance career and a self-invested personal pension too. When it comes to his other money, he says around 60 per cent is in an investment account, 20 per cent in an ISA and 20 per cent in cash savings. He also has a collection of modern antique chairs which he has built up over the last 14 years and have a large value. Stuart said: “Right at this moment, I have stopped saving, just while I rebuild my income fractionally. The end game is to secure my target income and then I’ll restart my savings for retirement. “The end date? I’m not sure I’ll stop at any point, but due to not having the greatest history of health, at least I have the flexibility to decide.”
I’m 57 with nearly £1m in my pension – here’s why I’m not retiring yet
Full Article
Original Source
Read the full article at Inews →KhanList aggregates and links to publicly available news content. We do not host full articles from third-party sources. Always verify important information with original sources.