
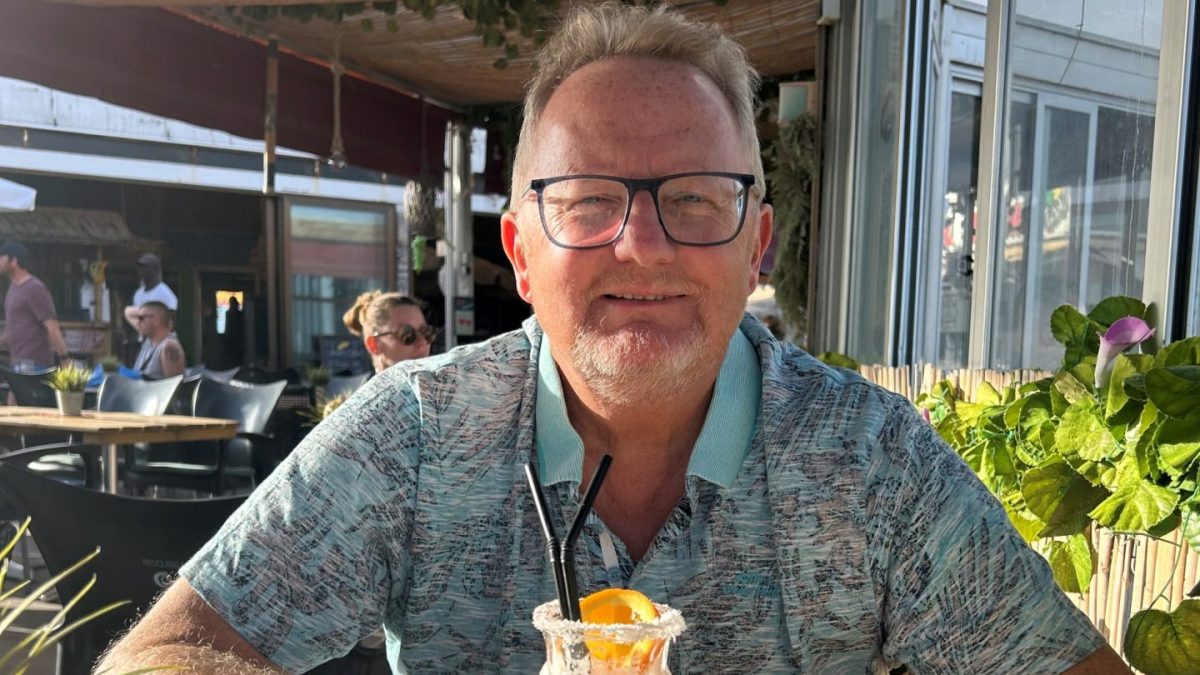
Two years ago, Chris Elliott took the decision to take semi-retirement after a period of ill health. Chris, then 60, started to take a look at how he would fund his lifestyle. He had a mixture of a private pension pot and cash savings, plus an entitlement to an annual retirement income from his time working in local government that he could access. Crucially, he knew he had seven years before he would start receiving his state pension. Shorts One option was to keep his private pension invested and to draw money from it flexibly – but in the end, Chris decided he wanted certainty, and opted for an annuity. This is a financial product that trades a lump sum of money – usually pension savings – for a guaranteed, regular stream of income. For years these have been out of favour because retirees saw them as bad value, but though they still represent a relatively small portion of the market, their popularity is growing. Chris, who lives with his wife in Staffordshire, got a seven-year flat rate annuity worth £30,000 a year, costing £300,000. This takes him to state pension age, at which point, he’ll also get a lump sum worth £180,000. “I wanted certainty for that period between retirement and when the state pension kicked in. And the volatility and noise around markets led me to value peace of mind on income over staying invested,” Chris says. Two years after taking the decision, Chris is happy. “I don’t regret it, as the annuity rate was good even if markets have continued to rise,” he says. Chris’s choice is one an increasing number of over-55s are taking, with sales of annuities increasing by 13.2 per cent to 100,144 in the year to March 2026. Experts believe the reasoning is two-fold. “Attractive annuity rates and the certainty of a guaranteed income remain important drivers,” says Pete Cowell, head of annuities at Standard Life. How do annuities work? Annuities allow pensioners to buy a set annual income in return for their pension pot. There are multiple different types, including: Lifetime annuity, which pays a guaranteed income for your whole life. Fixed-term annuity, which pays a guaranteed income for a set period of time. There are also other considerations too. A level or flat-rate annuity, like Chris’s, pays a set amount over the period, which doesn’t increase in line with inflation, causing its buying power to fall over time. You can also get index-linked annuities, which go up in line with inflation or certain other indices. These tend to be more expensive. Chris admits he is worried about the impact of inflation on his £30,000 payment – “I expected an average of 2.5 per cent but it looks like it could get worse” – but he has other savings he could use if it becomes a large problem. Annuities are usually bought with a defined contribution (DC) pension pots – the most common type nowadays. For those who have a defined benefit (DB) pension, often known as a final salary pension, they already get a steady stream of income each year in retirement. The main alternative to an annuity for someone with a DC pot is using something known as drawdown, where you leave your money invested in your pension pot, and draw from it flexibly as and when you need. The money you don’t take stays invested, so it generally grows over time, though it can also fall if the assets it is invested in start to shrink. Why are more people getting annuities? “Higher interest rates and gilt yields have transformed annuity rates, allowing retirees to secure significantly higher levels of guaranteed income than was possible just a few years ago,” said Adam Cole, retirement specialist at Quilter. Annuity providers heavily invest in government debt – known as gilts – to provide their payouts. Gilt yields – the return for investing in this government debt – are at multi-decade highs at the moment, because geopolitical uncertainty and high inflation mean investors are demanding a big return to offset the risk of investing their money. The higher rates are meaning the amount retirees get each year when buying an annuity is increasing – which makes them better value. Data from financial services provider Legal & General shows that in 2021, a healthy 65-year-old using £100,000 of pension savings could have bought a single-life annuity paying around £4,860 per year. Today, that same £100,000 could secure approximately £7,700 per year – approaching £3,000 extra in annual income. A second key factor behind the rise in retirees taking annuities is a desire for a fixed income, rather than what some see as taking on risk by keeping money invested. This was a key driver behind Chris’s decision. “I valued the certainty over getting the absolute maximum amount of money,” he explained. Experts say other retirees are thinking similarly. Though investing in stocks has generally produced positive gains in recent years, there have been several moments where markets have dipped temporarily. This is evidenced in the graph below, which shows the value of the S&P 500 – an index of 500 large companies listed on stock exchanges in the United States. Some retirees are unprepared to take on the risk of seeing the value of their money fall at moments when they might want to withdraw it. “Against a backdrop of market volatility, inflation uncertainty and concerns about making retirement savings last, it is perhaps unsurprising that more people are choosing to lock in a secure income stream for life rather than take on all the investment and longevity risk themselves,” Cole added. How to choose whether to get an annuity – and which type to take? “Before buying an annuity it’s worth taking a step back and thinking about what role you want it to play within your wider retirement plans,” says Pete Cowell. If you’re worried about risk, one option is to move the money you have for drawdown into less volatile assets, like bonds and cash – it doesn’t have to be held in the stock market. You don’t have to take either an annuity or drawdown either, a half-half approach works too. Some people opt to use an annuity to cover basic needs and use drawdown for the rest. James Shattock, managing director of Protection and Retail Retirement at L&G, said this was becoming more common: “Many people want to benefit from the flexibility associated with drawdown alongside guaranteed income from an annuity.” But Cowell also says people need to be aware that all annuities aren’t the same. “While level annuities remain popular because they offer a higher starting income, others may prefer inflation protection or an income for a surviving partner through a joint-life annuity. “It’s also important not to underestimate the importance of health and lifestyle questions. Being open about factors such as existing health conditions, medication, smoking history or alcohol consumption could mean you qualify for an enhanced annuity and receive a higher guaranteed income.” You can go to a financial adviser when taking one out though you don’t have to. Cowells adds: “Whether someone takes advice or not, shopping around remains one of the most important steps. Services such as MoneyHelper can help people understand their options and compare providers which may offer different incomes and product features.”
I semi-retired at 60 – and traded my pension pot for a £30,000 annual income
Full Article
Original Source
Read the full article at Inews →KhanList aggregates and links to publicly available news content. We do not host full articles from third-party sources. Always verify important information with original sources.