
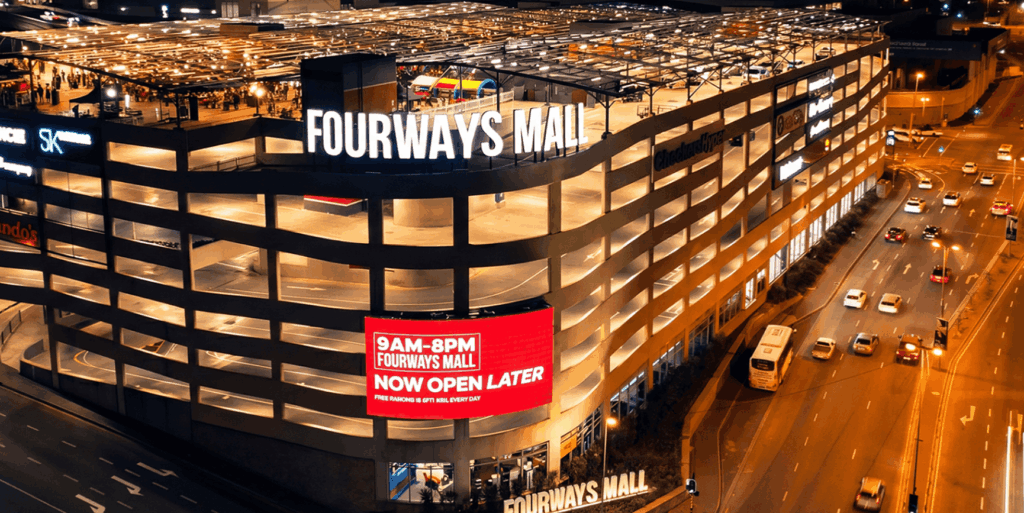
New 'upside' fee structure also firmly weds parties to each other for the next five years. The asset and property managers of Fourways Mall – Flanagan & Gerard (F&G) and Luvon (owned by Moolman Group family interests) – have been granted a call option to acquire a share of up to 15% in the property from co-owners JSE-listed Accelerate and Azrapart, an entity controlled by Michael Georgiou. The latter is currently in business rescue. The call option is included in a complex new property, development and asset management services agreement concluded by the parties. Shareholders will need to vote to approve the appointment of the managers. F&G and Luvon were originally appointed in February 2024, but towards the end of that year it was announced that certain conditions had not been fulfilled and that agreement had therefore lapsed. Still, both managers remained on site to render these services. The collapse of Azrapart into business rescue in June 2025 actually made approving the terms of a new agreement easier as the business rescue practitioners could be engaged directly. Georgiou ceased to be a director of Accelerate in October 2025. Turnaround The turnaround of the enormous 179 973m2 Fourways Mall under retail specialists Flanagan & Gerard and Luvon has been stunning. Whereas prior to their appointment, entire wings of the mall were practically unoccupied, vacancies have dropped from 18.8% in February 2024 to 6.6% in August 2026. Tenant turnover improved by 61%, from R226.3 million to R365.2 million, over that same period Trading densities are up from R1 816/m2 to R2 711/m2. Driving this has been increases across every visitor metric, including footfall (foot counters were first installed in September 2024), vehicle count and dwell time. Big change The opening this week of The View, a R100 million “luxury lifestyle food offering”, all but cements the turnaround. It introduces a convenience, food and restaurant offering to the mall that has been notably absent since its redevelopment and expansion in 2019. Tenants of this wing, with an iconic three-storey atrium, include The Pantry (by Marble), tashas, Fournos Bakery (relocated from the competing Fourways Crossing), Nossa Casa, Clay Café and George’s Grill. Co-working space Workshop 17 has also taken up a chunk of space and will open its fifth location in Johannesburg in this part of the mall, which is on the corner of Cedar and Witkoppen roads. Call option Accelerate and the business rescue practitioners (Piers Marsden and Lance Schapiro) say that because of these results, they “agree on the importance of regularising the appointment of the asset and property manager and retaining their services in order to unlock the full potential of the mall and its redevelopment potential and to harness additional value for shareholders”. The call option provides for the managers to participate in the upside going forward, and they are also protected with the introduction of a so-called “upside participation fee” that comes into play if their services are terminated before their five-year contract is up. There is a single performance hurdle here: that the normalised net monthly collections (effectively rent) doesn’t drop below a minimum level (R15.6 million for year one), with annual increases of CPI plus 1% for subsequent years. Effectively, the managers will be compensated for their role in growing collections above the current (base) level, using an agreed formula that excludes project funding and capex costs. In years three, four and five, the upside protection fees are R130 million, R140 million and R150 million respectively. Flanagan & Gerard and Luvon can elect to receive this fee as shares (a stake in the mall), or cash. The inclusion of this structure ensures that all parties, particularly the managers, are aligned to the single objective of unlocking the mall’s full potential. To date, they’ve put in an extraordinary amount of work for what was always going to be a long-term effort. All four parties are now firmly wedded to each other for the next five years (the exact start date will be determined following approval by Accelerate shareholders). The managers will be (and have been) paid three monthly fees: A property management fee (1% of gross monthly collections plus Vat); An asset management fee (1.75% of gross monthly collections plus Vat); and A leasing fee (0.5% of gross monthly collections plus Vat), billed a month in arrears. They are also paid development management fees of 2.5% of the total cost of each approved capital project. They are also paid development management fees of 2.5% of the total cost of each approved capital project. The mall is currently valued at R8.4 billion, with Accelerate’s 50% stake valued at R4.2 billion. This article was republished from Moneyweb. Read the original here.
Fourways Mall managers get option to buy up to 15% after steering turnaround
Full Article
Original Source
Read the full article at Citizen →KhanList aggregates and links to publicly available news content. We do not host full articles from third-party sources. Always verify important information with original sources.