
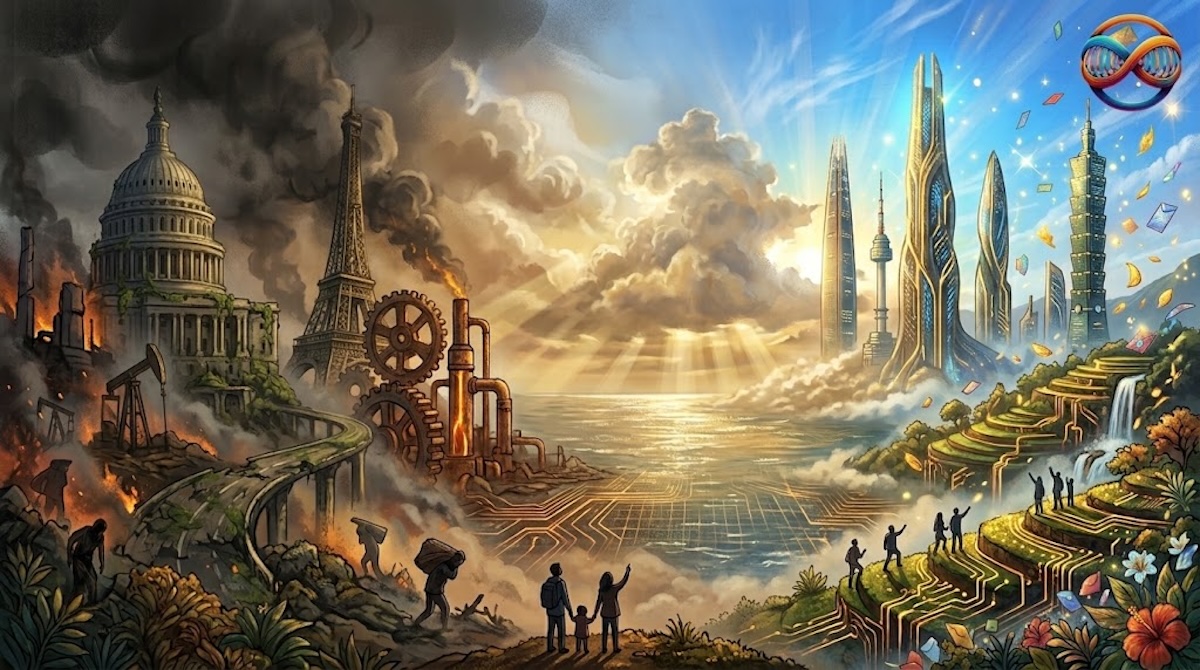
I am writing this from Singapore, where the haze is back. For the uninitiated, smoke from fires several hundred kilometres away drifts over the island, the skyline turns the color of weak tea and the whole city checks its air-quality app with a devotion normally reserved for share prices. Nothing here is on fire. It just smells as if it were. Markets have a haze season too, and we are in one. The smoke is blowing in from Washington and Europe, yet above Seoul and Taipei the skies have rarely been bluer. In the big capitals, the trouble is fiscal. Washington is running a deficit of 7-to-8% of GDP, on the IMF’s numbers. Paris is hunting for about US$60bn of savings while its debt heads for 120% of output. Beijing, ever the innovator, uses a tax app to remind its citizens that it would like 20% of whatever they earn offshore. However, Seoul and Taipei have the opposite problem: what to do with all the money. South Korea’s tax take this year is running about $47bn above budget, and next year’s corporate-tax line is more than twice the old record. Taiwan’s tax receipts rose 25% in the first eight months, to about $96bn, and nearly half of the increase came from the levy on share trading. Taipei has proposed sending every citizen about $310 in cash, with effectively no net new borrowing. In most capitals, “cash handout” and “no borrowing” do not appear in the same sentence. Yet, the market prices both as if they shared everyone else’s troubles. They don’t. The lazy reading puts the whole thing under “AI” as if Korea and Taiwan were a queue of data centers waiting for the next hyperscaler check. There is little credit for the fact that the chip boom is broader than that. It has given both a record run of exports and, behind them, two things no other large economy has this year: a household pay cycle that is only just starting and governments with cash to spare. In this note we discuss why we believe this is the opening stretch of a multi-year wealth cycle, like China’s after the global financial crisis, with one important difference. China borrowed its way into its boom. South Korea and Taiwan are being paid into theirs. In our article The Chip Economies, we argued that the windfall’s second-round effects “are not yet priced in.” Five months on, those effects are turning up in pay slips, property registers and tax ledgers. Share prices have yet to get the memo. The debt drag America grew at an annualiszd 2% in the second quarter – and close to half of that, on ING’s reckoning, came from computers, software and the buildings that house them. Private data-center construction ran at an annualized $85bn in August, up 73% in a year. America has one engine running, and it plugs into the wall. Beyond that one engine, the sky is grayer. Employers added 29k jobs in September, the kind of hiring that used to come with an apology, and pay growth has slowed to 3%. The saving rate fell to 4% in August, its lowest since November 2022, so more of the shopping is coming out of the cushion. Washington’s own books are in the same mood, with more zeros: the fiscal year that ended in September ran a federal deficit of US$2tn. The ten-year Treasury yielded 5% on 13 October. Lenders have noticed, and are charging accordingly. The local boom Now look east. Momentum money trades Seoul and Taipei as a US rate bet in an inconvenient time zone: both get sold within the hour by models that have never read a shipyard’s bonus notice. In July a 30 basis point rise in the US 10Y Treasury was blamed for knocking 22% off the KOSPI in a month. On July 15 a softer American inflation print for June added 6% to the KOSPI in a single day. Meanwhile the domestic engines have started firing, with little being noticed. Taiwan’s households spent 6% more in real terms in the second quarter, and total wages rose 8% in July. The pay calendar, from Lunar New Year bonuses to employee share plans, is written in Seoul and Taipei and runs to 2029. No CPI print in Washington moves a February bonus in Icheon or Taipei. And if a storm does blow in from abroad, both governments have the cash to be a safe port. South Korea: Nominal GDP rose 26% in the year to the second quarter. The cleanest measure is real national income (GNI), which counts what a country’s output can actually buy. It rose 16% while real output rose 4%. Korea is not making that much more stuff. It is being paid a great deal more for it. September exports hit a record US$121bn, up 84%, and the current-account surplus for January to August was US$279bn, four times last year’s. Taiwan: Real GDP rose 15% in the first quarter and 13% in the second, the strongest first half in fifty years. The statistics office expects 11% for 2026, a 39-year high. September exports hit a record US$87bn, up 61%. On the IMF’s latest numbers, the two governments’ debt ratios fall this year, Taiwan’s to 21% of GDP and Korea’s to 47%. The weather map: six economies in 2026 Screenshot Confessions of a non-economist I am not an economist. I have spent my career in Asian equities sitting next to some very good ones. An economist’s job is to tell you, carefully and with revisions, what has happened, and the profession is right to wait for the data. Rear-view mirrors are essential equipment. Managing a fund is a different trade. We are paid to squint through the windscreen, guess where the road bends and, now and then, notice when a price has wandered a long way from what it is worth. From my seat, Korea and Taiwan are being priced for somebody else’s storm. MSCI Korea trades on five times forward earnings, three standard deviations below its own history. Analysts have raised its 2026 profit forecasts by about 240% this year, and pencil in another 28% of growth for 2027. India, a fine market with a fine story, trades on about 21 times. Korea costs about a quarter as much, and, as the table shows, not for want of returns. In September foreigners sold $17bn of Korean shares and Korean companies bought back $23bn. Every sale has a buyer, so we read nothing into the flow, except perhaps which side had the closer view of the accounts. Taiwan is not cheap on a headline multiple, but it has gotten cheaper while getting richer: its forward P/E fell from 22 times in May to 19 times in September as analysts raised 2026 and 2027 earnings by another 4% and 5% in September alone. Nothing in that multiple pays for 11% real growth, a falling debt ratio, a cash handout or a nation of new shareholders. The discount for sunshine is what the market charges for a better forecast. More than just silicon Back to that lazy reading, in which Korea and Taiwan are two memory chips and a server rack wearing national flags. September’s trade data disagree. Strip out semiconductors and South Korea’s exports still rose 23%. The shipyards are booked into 2029, transformers and switchgear are sailing to an American grid that cannot get enough of them, and Korea’s defense makers carry three to five years of orders from Europe and the Gulf. Taiwan’s exports outside electronics and ICT rose 25% in September, the fastest in about five years. These customers, from shipowners to American utilities, have budgets of their own and very few suppliers who deliver on time. Strip out the chips and the order book still grows. Additionally, while the easy trade is to think that all silicon is for data centers, the reality is that it has moved into the rest of life. Today’s car carries roughly US$1,000 of semiconductors, and S&P Mobility expects more than $1,400 by 2030. The world installed 542,000 industrial robots in 2024, twice as many as a decade earlier, and South Korea runs 1,220 of them for every 10,000 factory workers – the highest density on earth. Robots need eyes too: Taiwanese brokers expect the island’s sensing-chip designers to grow sales by about 22% next year. None of this is a fashion purchase. South Korea became a super-aged society in December 2024, with more than a fifth of its people over 65, and Taiwan followed in 2025. Korea expects its working-age population to shrink from 37m in 2023 to 27m by 2044: more than nine million pairs of hands gone. A society running out of hands buys machines that have them. So does the rest of the aging rich world, and most of those machines need a chip made in Taiwan and memory made in Korea. Everyone gets an envelope The second lazy story says AI made a few thousand memory engineers rich and left everyone else to admire their cars. Start instead with someone who has never touched a wafer. This February a Korean shipyard paid its staff a bonus of 400% of base monthly pay, and exactly the same to its subcontractors’ workers. Power-equipment makers, whose transformers America’s grid is queueing for, paid their rank and file around 1,180–1,195% of base monthly pay, a year’s base salary in a single envelope. Who else gets an envelope, and when it lands: Taiwan’s pay slips tell the same story with less shouting. Average pay across all listed companies rose 7% in 2025, to about US$45,500, and 22 industries outside chips raised pay too. The club of listed companies paying an average of more than US$62,500 now has 118 members and about 207,000 people on the payroll. At a job fair beside TSMC’s new packaging plant in Chiayi, a farming county, 22 chip suppliers turned up offering US$1,250–1,875 a month. Rice paddies have rarely had such generous neighbours. Then come the construction crews, who are paid long before any engineer opens a letter. More than 20k people a day work at Samsung’s Pyeongtaek site, and SK hynix’s Yongin site expects up to 26k a day when the build reaches full strength early next year: on our estimate, about US$3bn of site wages in 2027. And then there are the owners. Some 14m Koreans held listed shares at the end of 2025, more than one Korean in four, and TSMC had 3m shareholders by Setpember 2026 vs 1.2m as at the end of 2023. The one-off that isn’t a one-off Bonuses were supposed to be a lucky year’s thank-you note. Yet, they are turning into furniture. Samsung’s chip bonus sits inside a ten-year agreement, and SK hynix has committed to paying staff 10% of operating profit for ten years. Both are uncapped, so each year’s payday tracks that year’s profit. One shipyard union now wants 30% of operating profit, which is the chipmakers’ formula with a bigger number. Taiwan has gone a step farther and written it into the rulebook. The regulator requires all 1,874 listed and OTC companies to set aside a fixed share of every year’s profit for staff earning about US$1,970 a month or less. Profit sharing for the factory floor is now annual by rule. Once a windfall has a formula, a regulator and brokers publishing per-head estimates of next year’s payout in January, nobody calls it a windfall any more. They call it payday, and put it in the diary. The diary is staggered, which is half the reason the market misreads it: quarterly profit shares, Lunar New Year bonuses, February cash, spring shares and summer top-ups, then again every spring until 2029. No single month carries the whole payment, so no single month’s retail-sales figure can catch it. The wedding and the car park Which brings us to the soft retail numbers. Korea’s monthly retail sales have been lumpy this year, and every lumpy month brings a fresh note asking where the consumer went. The answer comes in four parts. The income arrived. It sits in that 12-point gap between real national income and real output: money in Korean pockets that a retail print never sees. Households saved it first. In 2025 Korean households put aside a record $201bn more than they borrowed. Families that come into money pay down the card and build a cushion before they shop: the American habit run in reverse. Then they bought homes. The Bank of Korea followed SK hynix’s February bonus into the districts around its fabs. Residents there outspent the rest of Korea on their cards by up to 4% a month, but the share of each bonus that went to the shops fell, from 27% in 2025 to 21% in 2026, because a bigger share went into property. The bonus did not skip the mall. It stopped at the real estate agent first. The biggest checks haven’t been written yet. Korea’s two chipmakers will pay about $43bn of profit share on 2026 earnings between February and April 2027, on our estimate. Judging this cycle on October’s retail sales is like reviewing a wedding from the car park before the doors open. Postcards from a boom If you prefer your proof without a spreadsheet, follow households in the order they spend: the house, the car and then the passport. The house: Seoul apartment prices have risen for 87 weeks in a row, the longest run on record. Prices in Dongtan, beside Samsung’s Hwaseong fabs, rose 16% in the year to early August. In Taiwan, new homes in Hsinchu cost about US$6k per square meter, 21% more than a year earlier, and new-home prices in Kaohsiung, where TSMC is building its newest fabs, are up 16%. Hsinchu engineers have taken to phoning developers for a group-buy price before the pre-sale even opens, the way the rest of us club together for a takeaway. The car: Korea registered around 280k imported cars in the first nine months, up 24%. In Icheon, SK hynix’s home town, imported-car registrations rose 81% in the month the bonus landed. The passport: Koreans and Taiwanese made up 47% of all visitors to Japan between January and August, and this year their extra two million visitors have filled more than half the gap left by China. In August Koreans set a record for the month, at 850k, and Taiwanese visitors passed 700k in a month for the first time in July. One epicenter now spends in the other: 186k Taiwanese went to Korea for medical treatment in 2025, up 120%, nearly nine in ten of them for skin or cosmetic work. The broker and the shop are busy too: Taiwan opened about 990k securities accounts in the first nine months, its biggest year on record, and a senior merchandizer at a global luxury house told an industry call that in South Korea “many people who did not previously buy luxury have entered the market”. Rolling in it The governments are rolling in it, too. South Korea’s finance ministry has spent the autumn counting. On September 30 it put 2026 national tax at about $357bn, which is where that $47bn overshoot comes from. For 2027 it expects about $436bn, up 41%, with the corporate-tax line we started with at about $162bn, against a 2022 record of less than half that. Seoul has chosen to bank most of it. The new Future Response Fund holds tax above its ten-year trend: about $121bn, of which $78bn sits in reserve, $34bn is spent and $9bn goes to repay debt. Taiwan is running the same play with a different accent. That share-trading levy – the source of about 46% of this year’s rise in tax receipts – stays at home, whoever does the trading, so a nation of new shareholders is also a nation of new taxpayers. On August 17 President Lai put a price on that cash handout, about US$7bn, in a budget he called balanced, “with effectively zero borrowing.” Put the pieces together and these two treasuries are the safe port in the storm we promised: an internal safety net, already paid for. Behind them sit foreign-exchange reserves of US$601bn in Taiwan at the end of September and about $422bn in South Korea at the end of July. Most governments meet a rainy day by reaching for the credit card. These two can reach for the savings jar. Don’t throw out the baby with the bathwater The market has been taking America’s temperature and prescribing for Seoul and Taipei. Put down the broad brush and read their own numbers: record exports well beyond chips, pay rising from the shipyard to the factory floor and treasuries that pay down debt while mailing checks to citizens. That is roughly how China looked in 2009, at the start of a wealth cycle that ran for years, and whose biggest winners served the newly rich rather than making the exports. Here the pay calendar is written out to 2029 and, in Taiwan, into the rulebook. Year one already has dates on it. And unlike China’s, this one is paid, not lent. Haze seasons end the way they begin, without asking anyone’s permission. The wind turns, the skyline comes back, and people wonder how they spent weeks squinting at buildings that were there all along. Those who make money spend money. The market is throwing out the baby with everyone else’s bathwater. We would rather keep the baby. Gary Pinge is a senior analyst with the GenInnov Epicentres Fund. This article, originally published by GenInnov, is republished with permission.
For Seoul and Taipei markets, blue skies above the haze
Full Article
Original Source
Read the full article at Asiatimes →KhanList aggregates and links to publicly available news content. We do not host full articles from third-party sources. Always verify important information with original sources.